Insurance Claim Process: Buying an insurance policy is only the beginning. The real importance of insurance becomes clear when an unexpected event occurs, and you need financial support from the insurer.
Whether it is a health insurance claim after hospitalization, a motor insurance claim after an accident, or a life insurance claim after the policyholder’s death, the process generally follows a series of steps. Knowing these steps in advance can help you avoid unnecessary delays, missing documents, and communication problems.
The insurance claim process may look complicated at first, but it becomes much easier when you understand what happens after the claim is reported.
From claim intimation and registration to document verification, assessment, and final settlement, here is a detailed guide to the insurance claim process in simple language.
What Is an Insurance Claim?
An insurance claim is a formal request made by the policyholder, insured person, or nominee to an insurance company for payment of a covered loss or benefit under the policy.
For example, if your insured car is damaged in an accident, you may raise a motor insurance claim. If you are hospitalized for a treatment covered by your health insurance policy, you may submit a health insurance claim.
Similarly, in a life insurance policy, the nominee may make a claim after the death of the insured person, subject to the policy terms and conditions.
The insurer then checks the policy, circumstances of the event, and supporting documents before deciding whether the claim is payable.
How Does the Insurance Claim Process Work?
Although the exact procedure varies between insurers and policy types, the journey usually looks like this:
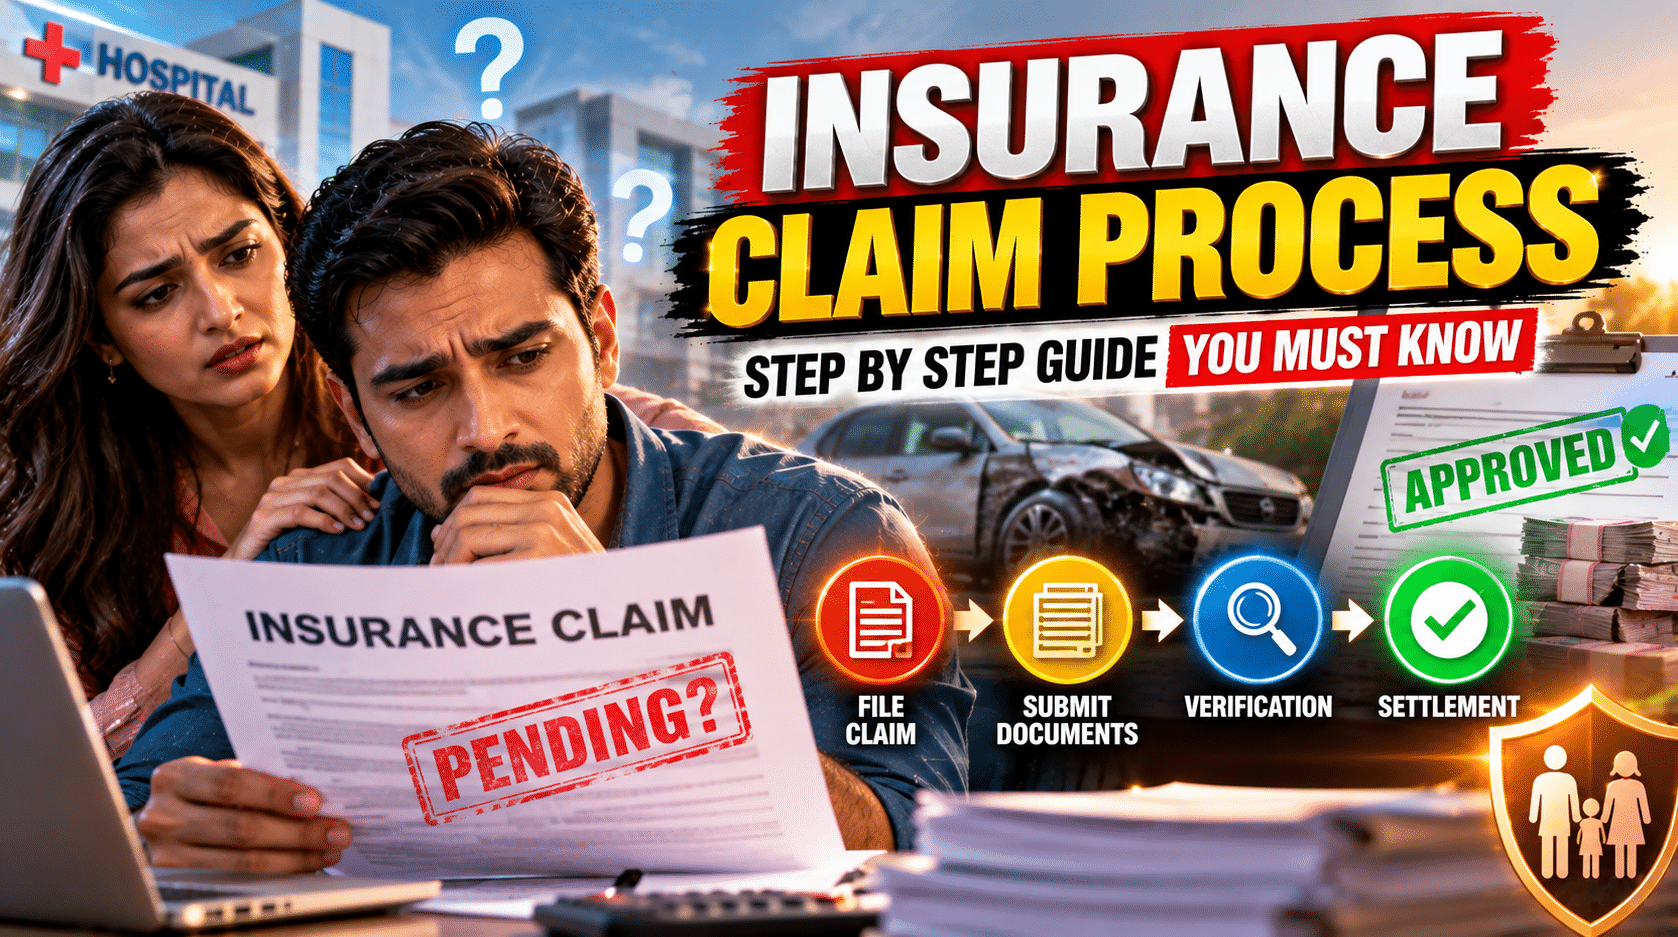
Incident occurs → Claim intimation → Claim registration → Document submission → Verification/assessment → Claim decision → Settlement or rejection
The first step is particularly important because insurers may prescribe specific timelines for notifying them about an insured event. LoansJagat’s insurance guidance also highlights prompt intimation as an important part of the claim process.
Let’s understand every stage.
Step 1: Inform the Insurance Company About the Incident
The first thing you should generally do after an insured event is inform your insurance company.
This is known as claim intimation.
Depending on the insurer, you may be able to report the claim through:
- Insurance company website
- Mobile application
- Customer care helpline
- Branch office
- Insurance agent or intermediary
While reporting the incident, keep basic information such as your policy number, date and time of the incident, location, and a brief description of what happened ready.
Do not deliberately delay the notification. The applicable time limit can differ depending on the policy and type of claim.
Step 2: Get the Claim or Reference Number
Once the insurer receives your claim intimation, it generally registers the claim and provides a claim number or reference number.
Keep this number safe.
It can become important when you:
- Check the claim status
- Communicate with the insurer
- Submit additional documents
- Follow up on a pending claim
- Raise a complaint about an unresolved claim
It is also a good idea to keep copies of emails, forms, receipts, and other communication related to the claim.
Step 3: Submit the Required Documents
After the claim is registered, the insurer will ask for documents relevant to the particular policy and incident.
The exact requirements vary considerably.
For example, a health insurance claim may require hospital records and medical bills, while a motor claim may involve vehicle documents, accident details, and repair estimates.
Common documents may include:
- Policy document or policy number
- Completed claim form
- Identity proof
- Address/contact details
- Bank account information, where applicable
- Bills and receipts
- Medical reports and prescriptions
- Hospital discharge summary
- Photographs of damaged property or vehicle
- FIR or police documents where applicable
- Repair estimates
- Death certificate for eligible life claims
- Nominee-related documents
- Any other documents requested by the insurer
For health claims, insurers can require medical records, bills, discharge summaries, investigation reports, and other supporting documents depending on the circumstances.
The most important point is simple: submit genuine, accurate and complete information.
Step 4: Claim Verification and Assessment
Once the documents are received, the insurer examines the claim.
Depending on the type of insurance, this may involve document verification, medical review, investigation, or physical assessment.
For example:
Motor insurance:
A surveyor or authorised assessor may inspect the damaged vehicle and assess the loss.
Health insurance:
The insurer or its claims administrator may examine medical records, hospital bills, treatment details and policy coverage.
Life insurance:
The insurer may verify the policy status, death-related documents, nominee information, and other relevant details before processing the claim.
The insurer may also ask for additional information if the documents initially submitted are insufficient.
Step 5: The Insurer Makes a Claim Decision
After completing the necessary checks, the insurer may:
- Approve the claim
- Ask for additional information or documents
- Approve only the amount payable under the policy
- Reject the claim if it is not payable under the policy terms
This is why simply having an insurance policy does not automatically mean every loss will be reimbursed.
The event must fall within the policy’s coverage and comply with its terms, conditions, and exclusions.
Step 6: Claim Settlement
If the claim is approved, the insurer processes the eligible payment according to the applicable policy and claim procedure.
The amount paid can depend on factors such as:
- Policy coverage
- Sum insured
- Deductibles
- Exclusions
- Depreciation, particularly in some motor claims
- Co-payment
- Policy limits
- Actual loss or eligible expenses
Therefore, the amount you receive may not always be equal to the total amount you originally claimed.
Cashless vs Reimbursement Insurance Claims
Health insurance commonly involves two broad claim routes: cashless treatment and reimbursement.
Cashless Claim
Under a cashless arrangement, eligible treatment is taken at a network hospital subject to the insurer’s applicable process and approval.
The insurer or claims administrator may coordinate with the hospital regarding eligible expenses.
However, “cashless” does not necessarily mean that every expense will be paid by the insurer. Non-covered items, deductibles, co-payments, and other policy conditions can still apply.
Reimbursement Claim
In a reimbursement claim, the insured person generally pays the eligible expenses first and then submits the required documents to the insurer for reimbursement.
Bills, receipts, medical records, and other supporting documents may be required.
The exact procedure and timelines depend on the policy and insurer.
What Documents Are Required for an Insurance Claim?
There is no single document list applicable to every insurance claim.
The requirements depend on the type of insurance and nature of the incident.
| Insurance Type | Commonly Required Documents |
|---|---|
| Health Insurance | Claim form, hospital bills, discharge summary, prescriptions, medical reports, ID and policy details |
| Motor Insurance | Claim form, policy details, vehicle documents, driving licence, photographs, repair estimate and police documents where applicable |
| Life Insurance | Claim form, policy documents, death certificate, nominee/claimant documents and other records requested by insurer |
| Property Insurance | Claim form, photographs, bills, ownership-related documents, loss assessment and police/fire records where applicable |
Always check the insurer’s specific document requirements because additional records may be requested during assessment.
Why Do Insurance Claims Get Rejected?
A rejected insurance claim can be extremely frustrating, especially when the policyholder expected financial support.
However, rejection does not necessarily happen because an insurer simply “does not want to pay.” The claim has to be assessed against the policy terms and available evidence.
Common reasons can include:
1. The Event Is Not Covered
If the loss falls outside the coverage provided by the policy, the claim may not be payable.
2. Policy Exclusions Apply
Every insurance policy has exclusions. These specify situations, expenses, or circumstances that are not covered.
3. Incorrect or Incomplete Information
Materially incorrect information supplied while purchasing the policy or making the claim can create problems during assessment.
4. Missing Documents
If important documents or evidence are not provided, the insurer may be unable to complete its assessment.
5. Policy Was Not Active
A claim generally cannot be paid for an insured event occurring outside the policy’s effective coverage period.
6. Claim Intimation Was Delayed
Some policies prescribe specific timelines for notifying the insurer. A delay can complicate the process and, depending on the policy and circumstances, may affect claim admissibility.
If a delay occurs for a genuine reason, inform the insurer and provide an explanation rather than simply ignoring the deadline.
What Should You Do If Your Insurance Claim Is Rejected?
Do not stop at the word “rejected.”
First, ask the insurer for the rejection decision and the specific reason in writing.
Then:
- Read the rejection reason carefully.
- Check the relevant policy clause.
- Compare the insurer’s explanation with your documents.
- Submit clarification or additional documents if appropriate.
- Approach the insurer’s Grievance Redressal Officer if the issue remains unresolved.
IRDAI’s Bima Bharosa guidance says policyholders should first approach the insurer’s Grievance Redressal Officer with a written complaint and supporting documents. If the response is unsatisfactory or the complaint is not resolved within the prescribed period, the policyholder can escalate the matter through Bima Bharosa/IRDAI’s grievance mechanism.
What Is Bima Bharosa?
Bima Bharosa is IRDAI’s grievance-redressal platform for insurance policyholders.
It allows consumers to register and track insurance-related complaints.
According to the official Bima Bharosa portal, a complaint generates a token number after successful registration, which can be used to track its status.
Importantly, the official portal also warns policyholders that Bima Bharosa does not ask complainants to make payments for processing complaints.
Therefore, be cautious if someone contacts you claiming that you must pay money or scan a QR code to receive an insurance claim.
How Can You Make the Insurance Claim Process Easier?
A few simple habits can prevent many avoidable problems.
Keep Your Policy Documents Organised
Maintain digital and physical copies of your policy documents, renewal details, and important contact numbers.
Read Exclusions Before You Need to Claim
Most people focus on the coverage amount while buying insurance and ignore exclusions. Understanding both sides is important.
Inform the Insurer Promptly
Do not wait unnecessarily after an insured incident. Follow the notification procedure and timeline mentioned in your policy.
Keep Original Documents Safe
Bills, medical records, receipts, police documents, and other evidence may be required during assessment.
Give Accurate Information
Never exaggerate the loss or provide incorrect details just to increase the claim amount. Inconsistencies can create complications during verification.
Keep Communication Records
Save claim numbers, emails, acknowledgement receipts, submitted documents, and important conversations.
Follow Up Using the Claim Number
If your claim is pending, use the official claim number while communicating with the insurer.
How Long Does an Insurance Claim Take?
There is no single processing time for every insurance claim.
A straightforward claim with complete documents may move faster, while claims involving investigation, multiple documents, medical review, disputed circumstances, or complex loss assessment can take longer.
For this reason, policyholders should check the specific policy terms and the insurer’s current claim-service timelines rather than relying on a generic number.
IRDAI’s grievance mechanism separately provides routes for complaints when an insurer does not resolve a policyholder’s grievance within the prescribed period.
Insurance Claim Process at a Glance
Here is the complete journey in simple form:
1. Incident occurs
↓
2. Inform the insurer
↓
3. Claim gets registered
↓
4. Claim/reference number is generated
↓
5. Documents are submitted
↓
6. Verification or assessment takes place
↓
7. Insurer reviews coverage and admissibility
↓
8. Claim is approved, partially settled, kept pending for information, or rejected
↓
9. Eligible amount is settled according to the policy
Final Takeaway
The insurance claim process becomes much less confusing when you know what happens after an incident.
The most important things are to inform the insurer promptly, keep your claim number safe, submit accurate documents, understand your policy coverage and exclusions, and maintain a record of every communication.
If a claim is rejected or remains unresolved, the policyholder still has formal grievance-redressal channels. The first step is generally the insurer’s own grievance mechanism, followed where appropriate by escalation through IRDAI’s Bima Bharosa system.
Insurance is ultimately about financial protection, but that protection works best when the policyholder understands both the coverage and the claim procedure before an emergency occurs.
Frequently Asked Questions (FAQs)
1. What is the first step in an insurance claim?
The first step is generally to inform the insurance company about the insured event through the available claim-intimation channel. The applicable notification timeline can vary according to the policy.
2. Can an insurance claim be filed online?
Yes. Many insurers provide online claim registration through their websites or mobile applications. Email and customer-care channels may also be available.
3. What is a claim number?
A claim number or reference number is the identifier assigned to a registered claim. It can be used to track the claim and communicate with the insurer.
4. Can an insurance company ask for additional documents?
Yes. Depending on the circumstances, the insurer may request additional information or documents needed to assess the claim.
5. Why can an insurance claim be rejected?
A claim may be rejected when the loss is outside policy coverage, an exclusion applies, required conditions are not met, important information is inaccurate, or the insurer cannot establish that the claim is payable under the policy.
6. What should I do if my claim is rejected?
Ask the insurer for the rejection reason in writing and review it against the policy terms. If you believe the decision needs reconsideration, submit the relevant clarification or documents and use the insurer’s grievance-redressal process.
7. What is the difference between cashless and reimbursement claims?
In a cashless claim, eligible expenses may be settled directly with a network provider subject to policy terms and authorisation. In reimbursement, the insured generally pays first and later submits eligible expenses and supporting documents to the insurer.
8. Can a delayed claim intimation cause problems?
Yes. Insurance policies may specify timelines for claim notification. Delayed intimation can complicate assessment and, depending on the policy and circumstances, may affect the claim.
9. What is Bima Bharosa?
Bima Bharosa is IRDAI’s insurance grievance-redressal platform through which policyholders can register and track complaints.
10. Can I complain to IRDAI if my insurer does not resolve my complaint?
Yes. IRDAI’s Bima Bharosa guidance provides an escalation mechanism when the insurer’s grievance process does not provide a satisfactory resolution within the prescribed period.