8 Types of Business Loans in India: Every business reaches a point when its next stage of growth depends on having enough money. A retailer may need additional inventory before a busy season, a manufacturer may want to purchase new machinery, and a startup may need funds to turn an idea into a working business. In each situation, the right financing can make a meaningful difference.
However, not every business loan is designed for the same purpose. Some loans help cover routine expenses, while others finance equipment, support expansion, or provide short-term relief when customer payments are delayed.
Choosing the wrong facility can create unnecessary interest costs and repayment pressure. The key is to match the loan with your actual business requirements, expected cash flow, and ability to repay.
In this guide, Insurance & Finance Review explains eight common types of business loans available in India in 2026, how they work, their potential advantages, and the factors you should consider before applying.
What Is a Business Loan?
A business loan is financing obtained to meet a company’s or entrepreneur’s eligible business-related requirements. Depending on the product, the money may be used for working capital, purchasing equipment, expanding operations, managing cash flow, or funding other approved expenses.
Banks, non-banking financial companies (NBFCs) and other eligible financial institutions offer different forms of business financing. Some facilities require collateral, while others may be available without traditional property security, subject to eligibility and lender policies.
The loan amount, interest rate, tenure, fees, and approval requirements depend on the applicant’s financial profile, business performance, and chosen product.
Before applying, identify whether you need a one-time lump sum, short-term working capital, or flexible access to funds over time. This simple step can help narrow down the most suitable options.
8 Different Types of Business Loans in India
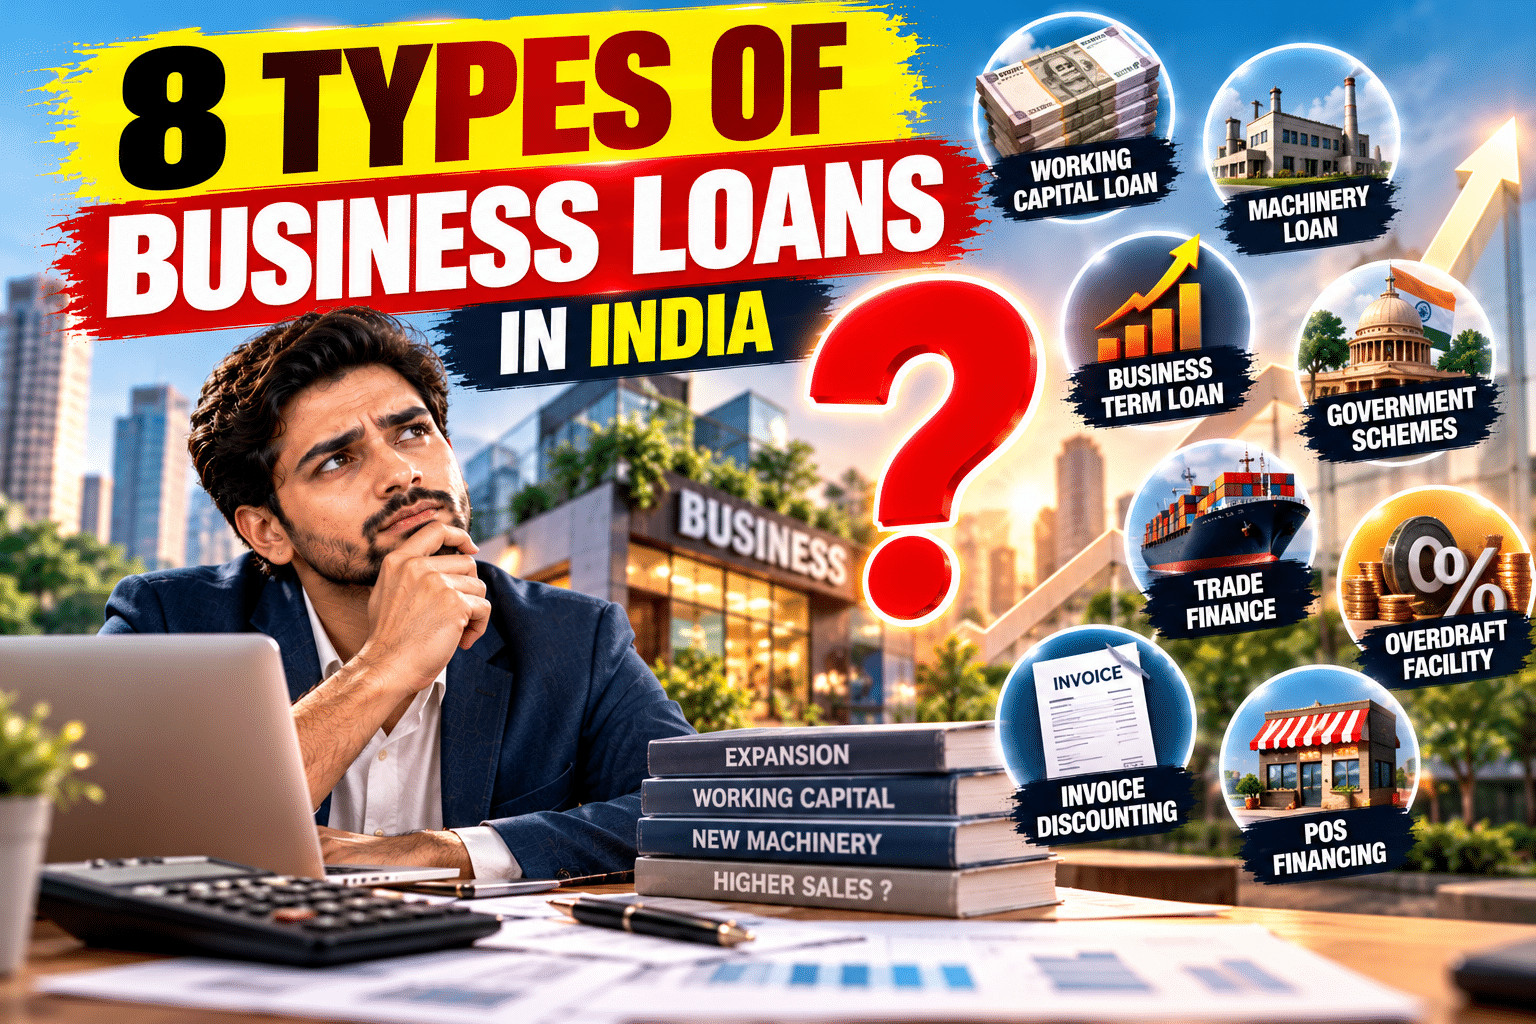
Here is a quick overview of eight common business financing options and the situations in which they may be useful.
| Business loan type | Main purpose | Potentially suitable for |
|---|---|---|
| Working capital loan | Day-to-day operational expenses | Retailers, traders and businesses with cash-flow gaps |
| Term loan | A specific investment or business expense | Established businesses planning expansion |
| Letter of credit | Supporting eligible trade transactions | Importers, exporters and businesses dealing with suppliers |
| Bill or invoice discounting | Accessing funds against unpaid invoices | Businesses selling goods or services on credit |
| Overdraft facility | Managing temporary cash shortages | Businesses with fluctuating cash-flow requirements |
| Machinery or equipment loan | Purchasing or upgrading equipment | Manufacturers, workshops and service businesses |
| Government-backed or scheme-based finance | Supporting eligible businesses under specific programmes | Qualifying MSMEs, startups and entrepreneurs |
| Point-of-sale financing or merchant cash advance | Obtaining funds linked to eligible sales or payment transactions | Certain merchants with regular digital sales |
The availability and terms of each facility vary by lender. Some are structured as conventional loans, while others are credit facilities or trade-finance instruments.
1. Working Capital Loan
A working capital loan helps businesses pay for routine operational requirements while they wait for revenue or customer payments to arrive.
For example, a shop may need to purchase stock before a festival season, or a small manufacturer may need to pay suppliers before receiving payment from buyers. Working capital financing can help bridge this temporary gap.
Typical uses include:
- Purchasing inventory or raw materials
- Paying eligible operating expenses
- Meeting supplier obligations
- Managing short-term cash-flow shortages
- Supporting payroll and other recurring business costs
Benefits of a Working Capital Loan
A suitable working capital facility can help a business maintain normal operations without waiting for every customer payment to clear. Depending on the product, financing may be available with or without collateral.
It can also help businesses handle seasonal demand, provided the additional revenue is sufficient to support repayment.
What Should You Consider?
Working capital loans are not usually the best choice for every long-term investment. Financing an asset that takes years to generate returns with a very short-term facility may put pressure on cash flow.
Check the repayment schedule, interest rate, renewal conditions, and any collateral requirements. Borrow only the amount needed to address the expected cash-flow gap.
2. Business Term Loan
A term loan provides a specified amount of money that the borrower repays over an agreed period, generally through scheduled instalments.
It may be useful when a business has a clearly defined investment in mind, such as opening another branch, expanding production capacity, or purchasing major business assets.
Common uses include:
- Business expansion
- Setting up a new office or outlet
- Purchasing eligible equipment
- Renovating commercial premises
- Funding a planned business project
Benefits of a Term Loan
A term loan can provide funds upfront, making it easier to plan a specific investment. The repayment schedule is generally established in advance, helping the business estimate its future financial commitments.
Term loans may be secured or unsecured, depending on the lender, amount, and borrower profile.
What Should You Consider?
The EMI must remain manageable even if sales grow more slowly than expected. A business should also account for processing charges, applicable fees, and the possibility of delayed returns from the investment.
Before borrowing, estimate how the financed project will generate enough cash flow to cover the loan repayments.
3. Letter of Credit
A letter of credit is a trade-finance instrument commonly used in eligible domestic or international commercial transactions. It provides a payment undertaking from a bank, subject to the terms and documents specified in the instrument.
For example, an importer purchasing goods from an overseas supplier may face a challenge: the supplier wants assurance of payment, while the importer wants confidence that the transaction will follow agreed conditions.
A letter of credit can help address this concern when the parties meet the relevant requirements.
Why Businesses Use Letters of Credit
- They can provide payment assurance to eligible suppliers.
- They may help businesses establish commercial relationships with new trading partners.
- They can support certain import and export transactions.
- They can clarify the documents and conditions required for payment.
What Should You Consider?
A letter of credit is not simply a cash loan deposited into a business account. It is a banking instrument governed by specific terms, documentation, and fees.
The applicant should understand the payment conditions, expiry date, required documents, bank charges, and obligations if the transaction does not proceed as planned.
Businesses involved in international trade should also consider foreign-exchange exposure and other transaction risks.
4. Bill Discounting and Invoice Discounting
Many businesses supply goods or services to customers who pay after 30, 60, or 90 days. Although the sale has been completed, the money may not arrive immediately.
Bill or invoice discounting can help eligible businesses access funds against certain unpaid invoices or receivables before their due dates.
For instance, a supplier that has issued an invoice to a creditworthy customer may use an eligible financing arrangement to receive funds earlier, subject to the provider’s terms and charges.
Benefits of Invoice Financing
- It can improve cash flow while customers take time to pay.
- It may help businesses purchase additional stock or fulfil new orders.
- It can reduce the need to wait for every invoice to mature before funding operations.
- It may support businesses that regularly sell to customers on credit.
What Should You Consider?
The financing provider may assess the customer, invoice, transaction history, and risk of non-payment. Not every invoice will qualify.
Compare the discounting fee, interest or other charges, recourse conditions and responsibility for unpaid invoices. The business should also ensure that the arrangement does not make its profit margins unnecessarily thin.
5. Overdraft Facility
An overdraft facility allows an eligible business to withdraw or use funds beyond the available balance in its account, up to an approved limit.
It is commonly used to handle temporary cash shortages rather than to finance every long-term investment.
For example, a business may need to pay suppliers today but expect to receive customer payments next week. An overdraft may provide short-term access to money during that gap.
Benefits of an Overdraft
- Flexible access to funds: The borrower can use money when required, within the approved limit and applicable conditions.
- Interest based on utilisation: Interest is often calculated on the amount used rather than the full sanctioned limit, although the precise calculation depends on the facility.
- Useful for changing cash flows: It may suit businesses whose income and expenses fluctuate throughout the month.
What Should You Consider?
An overdraft is not automatically a low-cost source of permanent funding. Interest, renewal charges and other fees may apply, and the bank can review the limit under the agreed terms.
Some facilities require collateral. If the overdraft is secured and the borrower defaults, the lender may take action in accordance with the agreement and applicable law.
Use an overdraft with a clear repayment plan rather than treating the available limit as additional income.
6. Machinery and Equipment Loan
Businesses that depend on physical equipment may need substantial funds to purchase, replace, or upgrade machinery. An equipment loan can spread the cost over a repayment period rather than requiring the entire purchase amount upfront.
This type of financing may be relevant to manufacturers, construction businesses, workshops, food-processing units, and certain service providers.
Common uses include:
- Purchasing production machinery
- Upgrading existing equipment
- Buying eligible commercial equipment
- Improving manufacturing capacity
- Replacing outdated business machinery
Benefits of Equipment Financing
It can help a business acquire an asset while preserving some working capital for routine expenses. The equipment may also improve productivity, reduce downtime, or increase output if the investment is commercially sound.
Depending on the product, the financed equipment itself may serve as security. Other collateral or guarantees may still be required.
What Should You Consider?
Do not evaluate an equipment loan only by looking at the monthly instalment. Consider maintenance costs, insurance, installation, staff training, downtime, and the equipment’s expected useful life.
The asset should generate sufficient business value to justify the total financing cost.
7. Government-Backed and Scheme-Based Business Loans
The Government of India supports eligible businesses through various credit and entrepreneurship programmes. These initiatives may aim to improve access to finance for micro, small and medium enterprises (MSMEs), entrepreneurs and other qualifying applicants.
Depending on the programme and its current rules, assistance may be delivered through banks, eligible financial institutions or other authorised channels.
Examples of programmes and frameworks that business owners may research include:
- Pradhan Mantri MUDRA Yojana (PMMY): Financing for eligible micro and small non-corporate, non-farm enterprises through participating lending institutions.
- Stand-Up India: A programme historically focused on facilitating bank loans for eligible SC/ST and women entrepreneurs establishing greenfield enterprises; applicants should verify its current operational status and applicable provisions.
- Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE): A credit-guarantee framework intended to support eligible lending to micro and small enterprises.
- Startup India initiatives: A broader set of measures supporting qualifying startups, some of which may improve access to funding or ecosystem support.
These programmes do not all operate in the same way. Some facilitate credit, some provide guarantees to lenders, and others offer different forms of support.
Potential Benefits
- May improve access to formal financing for eligible businesses.
- Some programmes can reduce the lender’s collateral-related risk through a credit guarantee.
- May support entrepreneurship, business formalisation and expansion.
- Can provide an alternative route for businesses that meet specific programme conditions.
What Should You Consider?
A government scheme does not automatically mean that every applicant receives a loan, a subsidy or a low interest rate. Eligibility, loan limits, collateral conditions, interest rates and application procedures differ by programme and lending institution.
Verify the current scheme guidelines through official government sources or participating lenders. Be cautious of agents who promise guaranteed approval in exchange for advance payments.
8. Point-of-Sale Financing and Merchant Cash Advances
Some merchants seek financing linked to their card transactions, digital payment activity, or future sales. Depending on the provider and product, these arrangements may be described as point-of-sale financing or merchant cash advances.
A provider may offer eligible businesses an upfront amount and recover it through an agreed share of future sales or another specified repayment mechanism.
This can appeal to merchants with regular digital transactions who need funds for inventory, seasonal demand, or other business requirements.
Potential Benefits
- Access to funds may be linked to the merchant’s transaction activity.
- Some products use a sales-based collection structure.
- The arrangement may suit businesses with fluctuating daily sales, depending on the terms.
What Should You Consider?
These products can be more expensive than conventional business loans, and the repayment structure may affect daily cash flow.
Do not compare financing options using the headline fee alone. Ask for the complete cost, including any factor rate, fees, repayment deductions, and the total amount payable. Where applicable, calculate an annualised cost to make comparisons easier.
Check whether repayments continue during periods of low sales, what happens if sales fall sharply, and whether personal guarantees or other security are required.
The product’s legal structure and terms matter more than its marketing label.
How to Choose the Right Business Loan?
The best financing option depends on why you need the money, when you expect to use it, and how your business will repay it.
Step 1: Define the Purpose
Start with a clear requirement. Are you buying machinery, financing inventory, expanding a branch or covering a temporary gap between sales and customer payments?
A specific purpose makes it easier to identify the right type of facility.
Step 2: Estimate the Required Amount
Prepare a realistic budget that includes the main expense and related costs. Borrowing too little may interrupt the project, while borrowing more than necessary can increase interest and repayment pressure.
Step 3: Review Your Cash Flow
Calculate how much money your business generates after paying operating expenses, taxes, salaries, and other obligations.
The loan repayment should remain manageable even if revenue is temporarily lower than expected.
Step 4: Compare Interest Rates and Total Costs
Compare the actual offers from different lenders. Review the interest rate, processing fee, documentation charges, collateral requirements, prepayment terms, and any other applicable expenses.
For products that do not quote interest in a conventional format, ask for the total repayment amount and a clear explanation of the pricing structure.
Step 5: Check Eligibility and Documentation
Lenders may review business vintage, turnover, profitability, bank statements, tax returns, credit history, and the applicant’s legal structure.
Prepare the requested records in advance, but do not assume that meeting a published eligibility requirement guarantees approval.
Step 6: Match the Tenure to the Purpose
Short-term requirements may be better suited to short-duration financing, while productive long-term assets may justify a longer repayment period.
Avoid financing a long-lived asset with a facility that must be repaid before the asset can reasonably generate returns.
Step 7: Read the Agreement Before Signing
Check the repayment schedule, applicable fees, collateral conditions, default provisions, and rules for early repayment. Make sure you understand the consequences of missing payments.
Business Loan Documents You May Need
The exact documentation varies by lender, loan type, amount, and applicant category. Commonly requested documents include:
| Document category | Examples |
|---|---|
| Identity and address proof | PAN, accepted identity proof and address documents |
| Business registration | Registration certificate, GST details where applicable, partnership deed or company incorporation documents |
| Financial records | Bank statements, balance sheets, profit-and-loss statements and cash-flow records |
| Tax documents | Income tax returns and other applicable tax filings |
| Business information | Business vintage, turnover, nature of operations and ownership details |
| Security documents | Property, machinery or other collateral records, if required |
| Additional paperwork | Loan application, existing liability details, guarantees or lender-specific forms |
Prepare genuine, consistent documents and submit them only through the lender’s authorised channels.
How to Improve Your Chances of Business Loan Approval?
No preparation can guarantee approval, but a well-organised application can help the lender assess your business more clearly.
- Maintain a healthy credit history: Pay existing EMIs and other credit obligations on time.
- Keep business accounts organised: Maintain clear records of sales, expenses, bank transactions, and tax filings.
- Demonstrate repayment capacity: Show how the proposed loan will fit into your expected cash flow.
- Reduce unnecessary debt: Review existing obligations before taking on another repayment commitment.
- Choose an appropriate loan amount: Request funding that matches your business requirement and financial capacity.
- Prepare a business plan: For expansion or equipment financing, explain the expected cost, business benefit, and repayment source.
- Compare lenders carefully: Eligibility rules, fees and approval processes differ, so review multiple offers where practical.
Common Business Loan Mistakes to Avoid
Even a useful loan can become a financial burden if the terms do not fit the business.
- Borrowing without a clear purpose: Avoid taking a loan simply because funding is available.
- Ignoring the total borrowing cost: Processing fees and other charges can make a seemingly attractive offer more expensive.
- Choosing an unsuitable repayment period: A very short tenure may strain cash flow, while an unnecessarily long one may increase total interest.
- Using short-term credit for long-term needs: Repeatedly renewing temporary facilities can create a cycle of borrowing.
- Assuming government assistance is guaranteed: Schemes have specific rules, and approval depends on the relevant programme and lender.
- Overlooking collateral risks: Understand what assets are pledged and what can happen if the business fails to repay.
- Not planning for slower sales: Build a repayment plan that accounts for seasonal fluctuations, delayed invoices, and unexpected expenses.
Final Verdict: Which Business Loan Should You Choose?
India’s business financing landscape offers several options for different commercial needs. A working capital loan may help with everyday expenses, a term loan can fund a planned investment, invoice discounting can unlock cash tied up in receivables, and equipment finance can support productivity improvements.
Trade-finance instruments, overdrafts, government-supported programmes and transaction-linked financing serve different purposes and come with different conditions.
The most suitable option is not necessarily the one offering the largest amount or the fastest approval. It is the one that matches your business objective, has a transparent cost structure, and can be repaid comfortably from realistic cash flows.
Insurance & Finance Review takeaway: Before taking a business loan, compare the total cost, repayment schedule, eligibility conditions, and risks—not just the amount you can borrow.
Frequently Asked Questions (FAQs)
1. What are the main types of business loans in India?
Common options include working capital loans, term loans, letters of credit, bill or invoice discounting, overdraft facilities, machinery loans, government-supported financing programmes and point-of-sale or merchant cash advance products.
2. Which business loan is best for a small business?
The right option depends on the purpose. Working capital finance may suit day-to-day expenses, a term loan may help fund expansion, and equipment financing may support machinery purchases. Compare costs and repayment terms before choosing.
3. Can I get a business loan without collateral?
Some lenders offer unsecured business loans to eligible applicants. Approval, loan limits, interest rates, and eligibility conditions depend on the lender and the applicant’s financial profile.
4. What is a working capital loan used for?
It helps businesses manage short-term operating expenses such as inventory, supplier payments, salaries, and other eligible business obligations.
5. What is the difference between a term loan and a working capital loan?
A term loan generally provides a specified amount for a planned expense or investment, repaid over an agreed period. Working capital finance is designed primarily to support everyday operations and short-term cash-flow needs.
6. What is invoice discounting in business finance?
Invoice discounting allows an eligible business to access funds against certain unpaid invoices before the customers’ payment due dates, subject to the financing provider’s terms and charges.
7. How does a business overdraft work?
An overdraft allows an eligible borrower to use funds up to an approved limit, even when the account balance is insufficient. Interest is generally charged on the amount used, according to the facility’s terms.
8. Are government business loans available to startups?
Some government programmes and lending initiatives support eligible startups and small businesses. Requirements vary, so applicants should verify the current rules and application process through official sources.
9. What documents are required for a business loan?
Lenders may ask for identity and address proof, business registration records, bank statements, tax returns, financial statements, and details of existing liabilities. Secured loans may require additional collateral documents.
10. Does a business need to be profitable to get a loan?
Requirements vary by lender and product. Some lenders consider profitability, turnover, business vintage, bank activity, credit history, and future repayment capacity. A particular loan may require a demonstrated operating history or profit record.
11. How can I compare business loan offers?
Compare the interest rate or pricing structure, total repayment amount, fees, tenure, collateral requirements, prepayment conditions, and consequences of default. Use the same loan amount and repayment assumptions wherever possible.
12. Can I use a business loan for personal expenses?
Business loans are generally intended for eligible business purposes. The permitted use depends on the product and agreement, so confirm the conditions with the lender before using the funds.
13. Are merchant cash advances cheaper than traditional business loans?
Not necessarily. Transaction-linked financing may have a different pricing structure and can be more expensive than conventional credit. Compare the total amount repayable, all fees, and the impact of repayments on daily cash flow.
14. How can I improve my chances of business loan approval?
Maintain a healthy credit profile, keep accurate financial records, demonstrate repayment capacity, choose a realistic loan amount, and submit complete documentation. Approval remains subject to the lender’s assessment.
15. Should a business borrow to expand?
Borrowing may make sense when the expansion has a realistic business case and projected cash flow can support the repayments. Estimate the investment cost, potential returns, operating expenses, and downside risks before taking on debt.